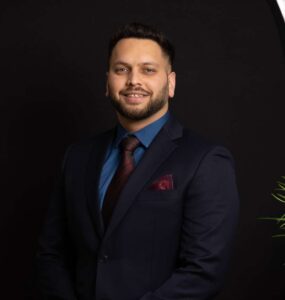
Rajveer Shah, Global Chief Strategy Officer at MITSUMI Distribution, spoke to CXO XPERTS about the forces reshaping India’s IT channel. He covered AI, cybersecurity, partner expectations, managed services and the company’s India strategy.
Which emerging technology is creating the most pull from Indian enterprises right now and how is Mitsumi preparing its portfolio and partners to meet it?
AI is creating the strongest pull. Indian enterprises are moving beyond pilots and asking how AI can run inside real business processes. That raises practical questions about computing power, data infrastructure, secure networks and skills.
Mitsumi is preparing with a clear direction rather than a finished list of offers. We are shaping our portfolio around the infrastructure and solutions AI depends on. We are also talking to partners about where they see demand building.
Partners need more than hardware knowledge. They need to understand use cases, data readiness and security. We want to help them build that understanding step by step, so they are ready with a credible answer when a customer asks about AI. We will share more as our plans take shape.
How are AI, cloud, and cybersecurity turning one-time sales into continuous customer engagement?
All three keep working, and keep changing, after the
first sale. An AI project grows as data grows and models are refined. Cloud is consumed over time, so usage rises and falls with the business. Cybersecurity is never finished, because threats evolve and protection must be updated, monitored and renewed.
The deal is no longer the end of the conversation. It becomes the start of regular reviews, adjustments and expansion. For partners, success is measured differently. A closed order matters less than a customer who stays, grows and trusts them for the next decision. Distributors can make this shift manageable by helping partners build the habits and skills that continuous engagement demands.
Which of these three offers the biggest growth opportunity for Indian channel partners in the next two years?
Cybersecurity. Every organisation is exposed, and awareness has reached the boardroom. Regulation and data protection expectations are tightening, and many small and mid-sized companies lack in-house expertise. They need a trusted adviser, and the channel is well placed to be that adviser.
The opportunity goes well beyond selling products. It covers assessments, deployment, configuration, monitoring support and periodic security reviews, all of which create lasting customer relationships. Security also sits inside the other two areas. AI projects need protected data, and cloud environments need strong controls.
AI will offer the longer runway, and cloud will keep growing. But in the next two years, security is where demand is most urgent and where a partner with the right skills can win business quickly.
Partners now expect more than product availability. What else do they look for in a distributor today?
Availability is the minimum. It no longer decides which distributor a partner chooses. Partners judge a distributor by how much it helps them win customers and keep them. Four expectations stand out.
Financial strength comes first. Partners want credit and working capital that fit how they trade, not rigid terms that squeeze cash flow. Technical depth comes next. They expect pre-sales support that helps them design the right solution and stand behind it. Speed and transparency follow: quick quotes, trackable orders and timelines that hold. Finally, presence matters. A distributor close to the market understands local demand, and a partner can reach a real person when a deal is on the line.
Trust runs through all four. Partners remember who kept a promise and who did not. The distributors that earn their loyalty say plainly what they can deliver, and then deliver it. That is the standard we are building towards in India.
Acer (computing) and Philips (displays) are now in your India portfolio. What made them the right brands to start with, and what do they bring to your partners?
Acer and Philips are live in our India portfolio today. They are where we begin, not where we stop.
Both are well-known names that buyers recognise, which makes conversations easier for partners from day one. Computing and displays are everyday needs in offices, schools, retail and public institutions, so demand is steady and broad. Many partners already sell in these categories and can start quickly on familiar ground.
These brands give partners recognised products, active demand and a route to build their relationship with Mitsumi. They also give us a foundation. As partners grow comfortable working with us, we can extend the conversation to a broader portfolio and more solution-led business.
What is the biggest risk to the Indian IT channel in the next three years and how should partners prepare?
Two risks stand out, and they feed each other: margin pressure and a skills gap. Product margins keep tightening as competition and direct buying increase. Partners who rely on them alone will find the business harder to sustain. Yet the alternative, services and recurring revenue, calls for skills many partners are still building.
A third risk is moving too slowly towards recurring models. They improve long-term stability, but they strain cash flow early on, and unprepared partners can struggle.
Preparation starts with choices. Partners should pick a few areas and build real depth in them, rather than spreading thin. They should invest in certifications and hands-on experience, and plan their working capital for the shift to recurring income. Above all, they should stay close to their customers, because relationships are what no competitor can copy quickly.
Which industries (BFSI, healthcare, manufacturing, e-commerce) are leading demand for managed services?
My view is that BFSI and healthcare lead demand, followed by manufacturing and e-commerce. This is a judgement drawn from how these sectors operate, not a figure from a dataset.
BFSI organisations work under strict security and compliance requirements, and they cannot afford downtime. Healthcare providers are digitizing records and services quickly, handle sensitive data and often have lean IT teams. Both benefit from experts who monitor and manage their environments around the clock.
Manufacturing is close behind, as plants connect their machines to IT systems that production can no longer run without. E-commerce completes the group. Its business lives online, so downtime costs sales at once and demand can spike without warning.
None of these sectors competes on IT. Routine monitoring, updates and support take time and skill they would rather put into the core business. A specialist partner takes on that load, and that is what drives demand for managed services.
Customers increasingly buy cloud and security directly from vendors. How do partners and distributors stay relevant in that model?
The direct-buy trend is real, and it is changing how the channel works. But buying a license is only the start of a technology decision. Partners and distributors stay relevant by adding value that a vendor cannot provide at scale. Vendors can sell a license, but they cannot sit beside every mid-sized customer in every city. Customers still need someone to fit new technology into their environment, support it locally and respond quickly when something goes wrong.
Partners stay relevant through integration, advice and ongoing support. They also combine products from several vendors into one working solution. Distributors stay relevant by enabling this, with access to multiple technologies, financing support and the services that help partners deliver.
The partners at risk are those who only pass licences through. Those who build real expertise will remain essential, because customers pay for outcomes, not for transactions.
How is Mitsumi using AI to support its partner ecosystem, for example in forecasting, inventory, credit decisions, or partner support, and what can CIOs and CTOs take from it for their own organisations?
We see clear potential in each of these areas, and we are exploring where AI can help. Better forecasting could improve stock planning. Smarter inventory decisions could shorten delivery times. Analysis could support credit decisions, and automation could speed up partner support. We are at the exploring stage, and I would not claim more than that.
For CIOs and CTOs, the approach carries some useful lessons. Start with a specific problem rather than a broad ambition. Get the data in order first, because AI is only as good as what it learns from. Run small pilots and measure the results honestly. Keep people involved in decisions that carry real consequences, such as credit. And expect the first version to be imperfect. Progress comes from learning quickly and improving steadily.
India is a price-sensitive, fast-growing market with strong regional differences. What is the one strategic bet Mitsumi is making here that it hasn’t made elsewhere?
Our bet is to build the India model properly from the start, instead of adding the important parts later. It has three pieces.
The first is services. In other regions, our value-added role grew over time. In India, we are designing it in from day one, alongside product distribution. The second is reach. Smaller cities sit at the core of our model, not at the end of a metro-first rollout. The third is our partners. We are putting their capability ahead of volume, investing in skills and readiness before revenue, so the ecosystem grows in step with the portfolio.
A price-sensitive market with strong regional differences punishes shortcuts. It is much harder to fix the foundations later than to build them right now.